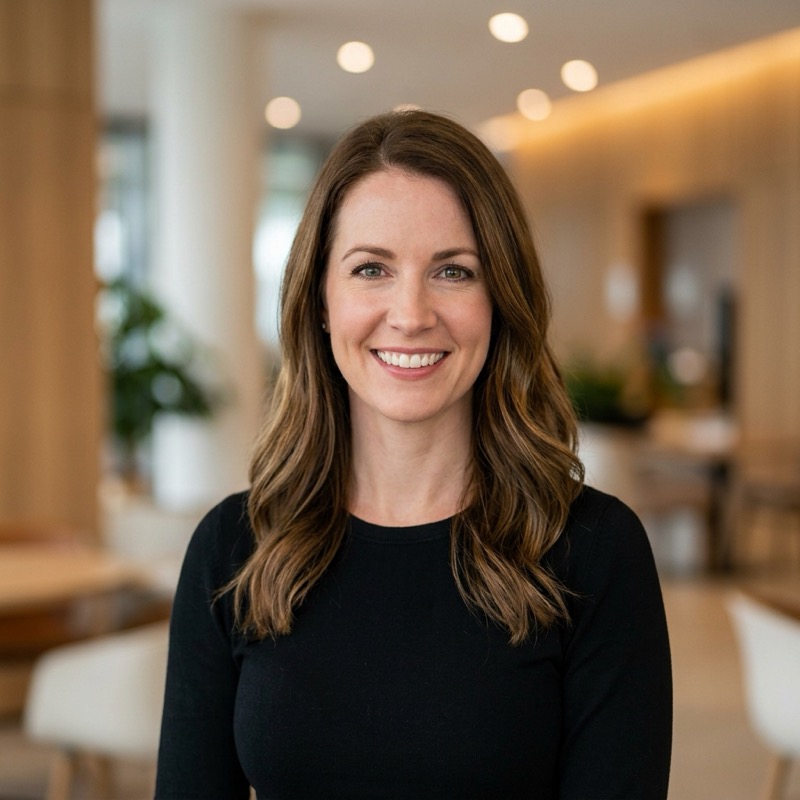
Camille Durand
“In fintech, 'move fast' was never the value. 'Fail loudly and cheaply' was.”
 - Martin Knapic, Product Moat
Camille Durand has spent fifteen years in fintech product, most of it learning that 'move fast' was never actually the value her industry optimized for - 'fail loudly and cheaply' was. She's Director of Product at Ledgerline in Paris and one of the more measured voices in this series on where AI has and hasn't earned trust.
Identity & Background
- Name
- Camille Durand
- Current role
- Director of Product
- Current company
- Ledgerline
- Location
- Paris, France
- Years in product
- 15 years
Your story: how did you end up in product?
I trained as an actuary, oddly enough - risk modeling, insurance math. A former colleague moved into product at a fintech and pulled me in to help scope a risk feature. I never left; the math background turned out to be more useful in product than I expected.
Core PM Philosophy
What's your decision-making philosophy?
Slow down at irreversible thresholds and speed up everywhere else. A credit decision that reaches a customer is expensive to reverse; a copy change is not. I tune the process to the cost of being wrong.
What's your biggest PM lesson or mistake?
Shipping a rule change without modeling its effect on a small segment first. It was technically correct and quietly excluded a group of legitimate borrowers. I now run a fairness check before, not after, anything touching eligibility.
How do you manage stakeholders?
Compliance and risk aren't reviewers at the end; they're in the room at scoping. It costs an hour early and saves weeks late, and it turns 'no' into 'yes, if' far more often.
Product & Decision-Making
What's your favorite product you've shipped?
An explainability panel that tells a declined applicant, in plain language, what would change the outcome. It reduced support contacts and, unexpectedly, improved the quality of reapplications.
AI & the Future
Which AI product do you use and respect?
Claude, mostly for summarising regulatory text and stress-testing my own reasoning. I never let it near a decision that touches a customer's credit.
Beliefs & Opinions
What's your unpopular product opinion?
Explainability requirements. Being forced to justify every automated decision in plain language has made our internal logic simpler and more defensible, model or no model.
Which author, thinker, or influence shapes you?
I let smaller, less regulated companies be the early signal. I watch what consumer AI products ship successfully for a full year before I even scope a version for our regulatory environment - the caution is deliberate, not a lag I'm trying to close.
Company & Product
What does your product solve?
Embedded lending infrastructure - the underwriting and compliance layer other fintech and marketplace apps plug in so they can offer credit to their own users without building a lending stack from scratch.
What's the biggest misconception about it?
Because a wrong answer about someone's money isn't a bad UX moment, it's a regulatory incident. Every AI feature we ship goes through the same scrutiny as a new lending model, and it should.
What's the market opportunity?
Our ICP is a mid-sized fintech or marketplace that wants to offer credit but doesn't have the twelve months and the compliance headcount to build it themselves. Against the largest embedded-finance platforms, we're narrower - lending only, not a full banking-as-a-service suite - and that focus is what lets us move faster on the compliance side specifically.
More from the conversation
What do you do away from work?
I restore antique clocks. Fintech and horology have more in common than people assume - both are about systems where a small, invisible error compounds silently until it's suddenly very visible and very expensive.
Any point you nearly changed direction entirely?
I considered leaving for pure risk consulting after a rough regulatory audit early in my career. I stayed in product because I realized I wanted to build the guardrail, not just diagnose that one was missing after the fact.
How big is your product org, and what's the company size?
Product is 18 people inside a company of about 220. I run the lending core specifically - three teams: underwriting, servicing, and compliance tooling.
Where has AI actually earned its place in your product?
Fraud pattern detection and support triage - places where the model flags something for a human rather than acting alone. Autonomy is the thing we're careful with, not intelligence.
How is AI changing your team's own processes, beyond the product itself?
Every model-assisted decision in the product now has a documentation trail generated alongside it, automatically, because a regulator will eventually ask for it. That requirement shaped our engineering process more than any feature request has.
What do younger PMs get wrong about fintech?
They assume compliance is a blocker to route around. It's closer to a design constraint, like screen size - annoying at first, and it usually forces a better answer than the one you started with.
What's a topic you think deserves more attention right now?
Model drift in credit decisions specifically - a model that was fair at launch can quietly become unfair as the applicant population shifts, and most fintechs don't re-audit fairness nearly often enough. I think this becomes a real regulatory flashpoint within a few years, not a hypothetical one.
Enjoyed this conversation?
A new interview with a product person lands every week. Get it in your inbox.